Who we serve > Stop-Loss Carriers
Examined
before it's paid. Documented before it's reimbursed.
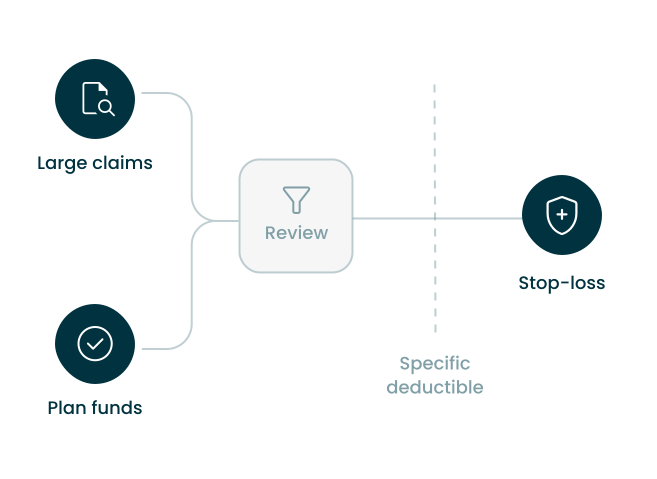
High-dollar claims arrive at reimbursement with the price already treated as settled. Highlight Health reviews them independently before the plan funds them, so what reaches the stop-loss layer is the right price the first time. Direct writers and MGUs both see the difference in what they end up paying.
Book a CallYou've seen the reports. You're living them.
Million-dollar-plus claims increased in frequency by 46% from 2022 to 2026.[1] Claims exceeding the specific deductible by at least $2 million have risen 213% since policy year 2020.[2]
Sun Life, High-Cost Claims and Injectable Drug Trends report, May 21, 2026 (70,000+ high-dollar claims, 3,300+ self-funded employers).
Tokio Marine HCC A&H Group, 2026 Annual Market Report announcement, June 1, 2026.
When the large claim comes in, the price arrives pre-baked: a billed charge, a network discount, a summary line. The plan is asked to fund it. The carrier is asked to reimburse it. The network-allowed amount is treated as the final word.
Audits and recoveries chase money after it's gone, while next year's premium prices off the loss that already landed.
What you get

A better loss ratio, at the source.
Reviewed claims resolve to examined amounts before reimbursement, not recovered amounts after. The reduction lands in this policy year's experience, where it changes the renewal instead of chasing it.

A determination that holds.
Every review produces a Documented Record that sits in the claim file before it's needed: supporting the coverage determination if it's disputed, and the cession when the reinsurer asks.

A book that renews better.
Better numbers on the year's worst claims, fewer surprises, fewer lasers, and a stronger quote when the group goes to market. That's a renewal story your brokers can sell.
In-network is not the same as examined.
Our reviews find issues on both sides of a claim: provider billing that doesn't match the record, and in-network allowed amounts that don't hold up against the contract, the published rates, or the hospital's own policies. The adjustments change what the plan funds and what the stop-loss partner ultimately pays.
You're Probably Wondering
Will review slow payment or put the plan out of compliance?


No. The review runs inside the payment standards the plan is held to, and the determination arrives within them.
How does this fit our MGUs, our TPAs, and our claim workflows?
One agreement, your triggers: specific deductible thresholds, diagnosis flags, first-notice reports. Direct writers and MGUs run it the same way. No workflow rebuild, no new obligations on your insureds.
We already have cost-containment vendors.
Most of what the market offers is out-of-network review or post payment recovery. The other claim reviewers don’t exhaust all avenues that should be explored. Highlight Health provides comprehensive independent review before payment, with the basis in the file. We accept no fees from the parties we review.
One agreement. Your triggers. Your book.
Carriers and MGUs engage Highlight Health directly. Review begins before the plan funds the claim, whether the claim is held in full or advanced against the specific deductible, and the plan-side relationships your business depends on stay where they are.

Not a carrier? Plans and their advisors bring the same review to their largest claims.
Start with the claims already over the deductible.
Bring one open large claim. We'll show you what review finds above the layer.