Who we serve > Brokers
Be the advisor who shows clients what's behind their largest claims
The system hands every advisor the same answers: trend, a discount percentage, a wait. We're the alternative: independent review of your clients' largest claims, in-network included, before they're paid.
Book a CallThe renewal meeting hasn't changed in years. The pressure has.
Your client's costs are up again, and the explanation is the same as last year: trend, utilization, a bad claim year. They nod, even though they remember hearing it before.
When a large claim hits, you're the first call. You ask the right questions and get a summary line, a discount percentage, and a wait. You know there's more behind that number. You can't get to it.
And the questions are getting harder. Corporate, union, and public-sector plans are being asked what they pay and why, and the advisors who guide them are part of that conversation now.
There's a better way, and it's yours to bring
Most advisors have never seen a large in-network claim examined before it's paid, because the system doesn't offer it.
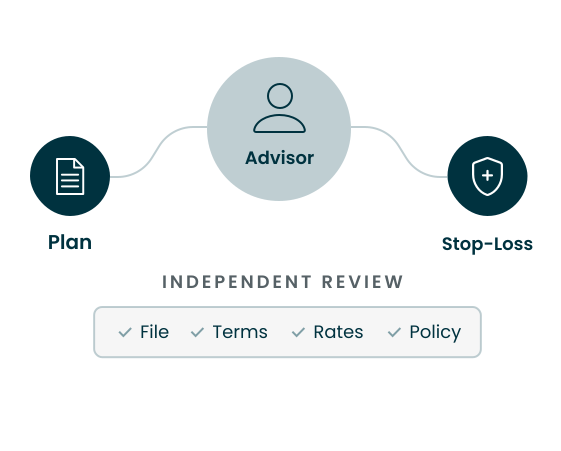
Independent review does: the full file, checked against the contracts, the published rates, and the hospital's own policies, before the money moves.
Your client sees it, brought by you. At renewal, you're not defending a trend line. You're presenting results with the evidence attached.
What you get

A reason to win the meeting
Independent review of large claims before payment is the thing most prospects have never been offered. You're the one who showed them.
Clients who stay for results
Lower paid amounts on the year's biggest claims, a stronger stop-loss story, and a record behind every number. Advisors who deliver that don't have to defend the relationship.
Standing you can point to
When fiduciary oversight is the question of the year, every review produces a Documented Record: independent evidence that the plan's largest payments were examined before they were made. You put it in place.
Proof
In-network is not the same as examined
Results reflect claims reviewed for multiple clients over two years. Outcomes vary by plan, claim mix, and documentation.
515
large claims reviewed, with nine in ten in-network.
$50M
in network-allowed charges resolved to about $20 million.
100%
of claims paid, settled, and on the record.
You're Probably Wondering
ERISA requires a payment determination within 30 days. Can a review fit inside that?


Yes. That clock runs from when the plan has the information it needs to decide, not from when the bill arrives, and a plan is entitled to that information first. Our review is built to finish within 10 days of complete documentation, inside the plan's normal payment window, with timing coordinated up front with the TPA and stop-loss partner.
My clients have been burned by cost-containment vendors before.
So have ours, which is why this works differently. Review happens before payment, on the contracts and published rates, and it never turns members into collateral. No balance-billing campaigns, no surprise letters to employees.
Will the TPA and stop-loss carrier cooperate?
Some make it easy. Some don't. We've delivered results across every kind of administrator, and we'll tell you up front what's possible with your client's setup, what it takes, and how their stop-loss partner can help. You walk in knowing.
Your client.
Your relationships.
Our lane.
We do one thing inside your client's plan: independent review of the claims big enough to matter, before they're paid. It sits alongside the TPA, the network, and the stop-loss placement you built. You decide which clients it fits and how to bring it; we give you what you need to decide, in confidence. Their part is measured in approvals, not hours.
Your client's side of this, and their stop-loss partner's.

Pick the client this would matter to most
Or just bring questions. Everything you share stays between us, and you'll leave knowing what a review would find and how to bring it to them.